Table of Contents
- LIC Housing Finance Home Loan Interest Rate 2026
- How LIC Home Loan EMI Calculator Based on Salary Works
- LIC Home Loan Eligibility Based on Salary 2026
- LIC Home Loan Eligibility Based on Monthly Salary
- LIC Housing Finance EMI on Different Loan Amounts
- LIC Home Loan Prepayment Calculator 2026
- LIC Home Loan Interest Savings with Monthly Prepayment
- LIC Home Loan Interest Savings with Annual Prepayment
- Monthly Prepayment vs Annual Prepayment
- LIC Home Loan Prepayment Rules and Charges 2026
- How to Use LIC Home Loan Prepayment to Close a Loan Faster
- How Existing EMIs Affect LIC Home Loan Eligibility
- LIC Housing Finance Home Loan Documents Required
- LIC Housing Finance vs Other Banks 2026
- FAQs – LIC Home Loan EMI Calculator with Prepayment Based...
Most home loan borrowers focus only on their monthly EMI when applying. But the true cost of a home loan depends on five factors working together: your salary, existing financial obligations, the applicable interest rate, repayment tenure, and any extra amounts you pay toward the principal.
This guide combines three search intents in one place: salary-based eligibility estimates, LIC Housing Finance EMI calculations, and practical examples of how prepayment can reduce your interest outgo and shorten your loan tenure.
You will see indicative borrowing capacity at different salary levels, EMI comparisons for common loan amounts, and estimates of how much interest you could save by paying ₹1,000 to ₹2,00,000 extra each month or year. All figures are illustrative calculations based on stated assumptions—not official LIC HFL sanctions or guaranteed savings. Actual terms depend on the lender\'s assessment and your loan agreement.
LIC Housing Finance Home Loan Interest Rate 2026
As of November 15, 2026, LIC Housing Finance has not publicly disclosed a single current starting home loan interest rate through its official channels. A Business Standard report dated November 5, 2026, citing Paisabazaar data as on November 4, 2026, indicates LIC Housing Finance\'s floor rate at 7.40%. A separate report from indiabank.net dated November 4, 2026, also lists LIC Housing Finance at 7.40%.
However, LIC HFL\'s own website displays only the LHPLR (LIC Housing Finance Prime Lending Rate) at 16.90%, effective from April 28, 2025. This is a benchmark rate, not the rate actually offered to home loan borrowers.
Given this discrepancy, applicants should confirm the latest applicable rate directly with LIC Housing Finance before applying. The 7.40% figure is a third-party reported floor rate and may not reflect the rate offered to your specific profile.
| Loan Information | Latest Available Details |
|---|---|
| Starting interest rate | 7.40% (third-party data as of November 4, 2026; confirm with LIC HFL) |
| Interest type | Floating (LIC HFL home loans are primarily floating-rate products) |
| Maximum tenure | Up to 30 years (subject to borrower age and retirement age) |
| Processing fee | 0.25% of loan amount, minimum ₹5,000, maximum ₹50,000 (third-party data; confirm with LIC HFL) |
| Prepayment conditions | Floating-rate individual housing loans: no prepayment charges |
Fixed or floating? LIC Housing Finance\'s home loans are primarily floating-rate products. A floating rate means your applicable interest rate adjusts when the benchmark changes. Borrowers with stronger credit profiles typically receive pricing closer to the lower end of the rate range; those with lower scores or \"new to credit\" status may be charged higher rates. Two borrowers with identical incomes receiving different rates is normal.
How LIC Home Loan EMI Calculator Based on Salary Works
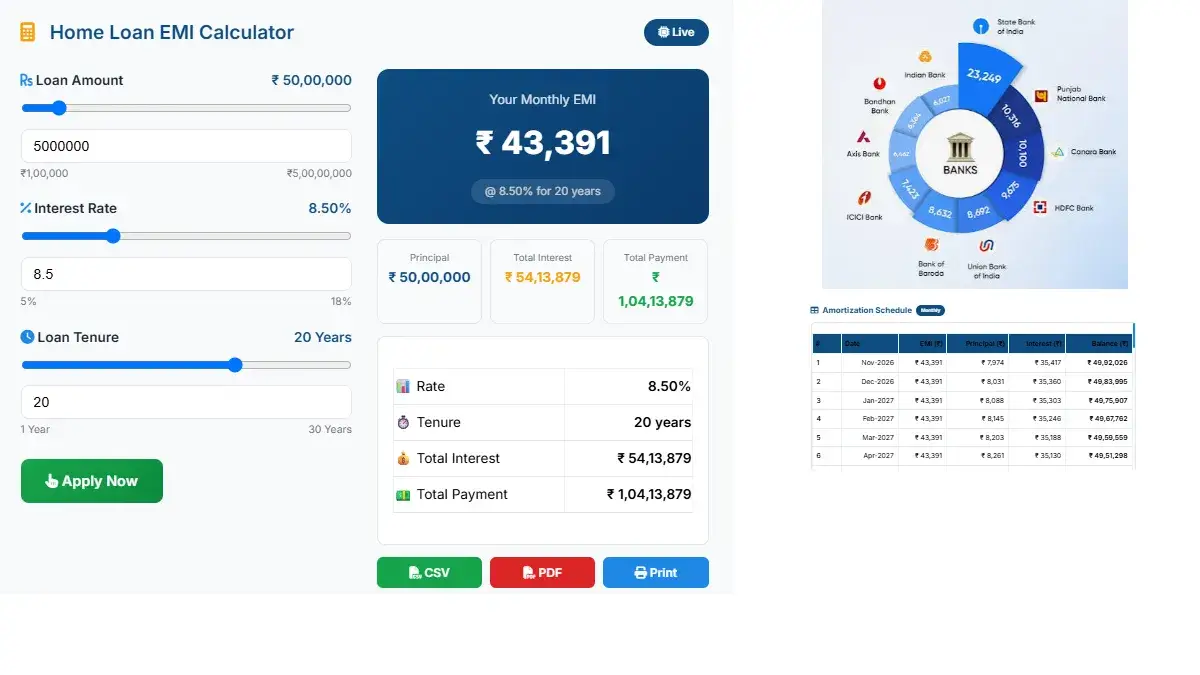
Home Loan EMI Calculator
Live| 📊 Rate | 8.50% |
| ⏱️ Tenure | 20 years |
| 💰 Total Interest | ₹ 0 |
| 💵 Total Payment | ₹ 0 |
Amortization Schedule Monthly
| # | Date | EMI (₹) | Principal (₹) | Interest (₹) | Balance (₹) |
|---|---|---|---|---|---|
| Calculating... | |||||
Three calculators serve different purposes: an eligibility calculator estimates how much you can borrow; an EMI calculator computes your monthly instalment from loan amount, rate, and tenure; a prepayment calculator simulates how extra payments change your repayment schedule and total interest.
The standard EMI formula is:
EMI = P × R × (1 + R)^N / [(1 + R)^N − 1]
Where P is the loan principal, R is the monthly interest rate (annual rate ÷ 12 ÷ 100), and N is the number of monthly instalments.
Steps to calculate:
Enter the proposed loan amount.
Enter the applicable annual interest rate.
Select the repayment tenure in years.
Calculate the monthly EMI.
Compare the EMI against your monthly take-home salary.
Adjust the loan amount or tenure to assess affordability.
All EMI calculations in this article use 7.50% annual interest as an illustrative rate. This is because LIC HFL\'s official November 2026 rate could not be verified from official sources. The 7.50% figure is close to the third-party reported floor rate of 7.40%, but it is not an official LIC HFL rate. Actual EMIs will depend on the rate sanctioned by the lender.
LIC Home Loan Eligibility Based on Salary 2026
LIC Housing Finance evaluates repayment capacity using multiple factors:
Net monthly salary: Take-home income after deductions.
Existing loan EMIs: Personal loans, car loans, education loans, and credit card obligations.
Employment stability: Employer type, years of service, and income consistency.
Age and remaining repayment years: Tenure typically cannot extend beyond retirement age (up to 30 years maximum).
Credit score and credit history: LIC HFL does not publish a hard cutoff, but higher scores typically mean lower applicable rates.
Monthly household expenses: Living costs, insurance, education, and other commitments.
Property value and LTV: Loan amount is capped by the property\'s value and applicable loan-to-value limits.
Co-applicant income (where applicable).
Two applicants with the same salary may qualify for different loan amounts because of differences in existing debt, credit history, and age.
LIC Home Loan Eligibility Based on Monthly Salary
The table below uses a 7.50% illustrative annual interest rate and a 40% illustrative EMI-to-income ratio (for planning purposes only, not an official LIC HFL rule), assuming no existing EMIs. Loan amounts are calculated using the reverse EMI formula and rounded to the nearest ₹0.1 lakh.
| Monthly Net Salary | Assumed EMI Budget (40%) | Estimated Loan Amount (20 years) | Estimated Loan Amount (25 years) | Estimated Loan Amount (30 years) |
|---|---|---|---|---|
| ₹25,000 | ₹10,000 | ₹12.4 lakh | ₹13.3 lakh | ₹14.3 lakh |
| ₹30,000 | ₹12,000 | ₹14.9 lakh | ₹15.9 lakh | ₹17.1 lakh |
| ₹35,000 | ₹14,000 | ₹17.4 lakh | ₹18.6 lakh | ₹20.0 lakh |
| ₹40,000 | ₹16,000 | ₹19.8 lakh | ₹21.3 lakh | ₹22.8 lakh |
| ₹50,000 | ₹20,000 | ₹24.8 lakh | ₹26.6 lakh | ₹28.6 lakh |
| ₹60,000 | ₹24,000 | ₹29.8 lakh | ₹31.9 lakh | ₹34.3 lakh |
| ₹75,000 | ₹30,000 | ₹37.2 lakh | ₹39.9 lakh | ₹42.8 lakh |
| ₹90,000 | ₹36,000 | ₹44.6 lakh | ₹47.9 lakh | ₹51.4 lakh |
| ₹1,00,000 | ₹40,000 | ₹49.6 lakh | ₹53.2 lakh | ₹57.1 lakh |
| ₹1,25,000 | ₹50,000 | ₹62.0 lakh | ₹66.5 lakh | ₹71.4 lakh |
| ₹1,50,000 | ₹60,000 | ₹74.4 lakh | ₹79.8 lakh | ₹85.7 lakh |
How to use this table: A 30-year tenure increases borrowing capacity by roughly 15% compared with a 20-year tenure at the same EMI budget, but total interest paid is significantly higher. If you have existing EMIs, subtract them from your budget first. For example, if you earn ₹50,000 and pay ₹5,000 toward a car loan, your effective home loan EMI budget at 40% is ₹15,000, not ₹20,000—corresponding to an illustrative loan amount of about ₹18.6 lakh for 20 years.
LIC Housing Finance EMI on Different Loan Amounts
The EMI figures below are calculated at a 7.50% illustrative annual interest rate. Again, this is a calculation assumption, not LIC HFL\'s official November 2026 rate.
| Loan Amount | 10 years | 15 years | 20 years | 25 years | 30 years |
|---|---|---|---|---|---|
| ₹10 lakh | ₹11,873 | ₹9,271 | ₹8,059 | ₹7,389 | ₹6,992 |
| ₹15 lakh | ₹17,809 | ₹13,907 | ₹12,088 | ₹11,084 | ₹10,488 |
| ₹20 lakh | ₹23,746 | ₹18,542 | ₹16,118 | ₹14,779 | ₹13,984 |
| ₹25 lakh | ₹29,682 | ₹23,178 | ₹20,147 | ₹18,473 | ₹17,480 |
| ₹30 lakh | ₹35,618 | ₹27,813 | ₹24,177 | ₹22,168 | ₹20,977 |
| ₹40 lakh | ₹47,491 | ₹37,084 | ₹32,236 | ₹29,557 | ₹27,969 |
| ₹50 lakh | ₹59,364 | ₹46,355 | ₹40,295 | ₹36,946 | ₹34,961 |
| ₹60 lakh | ₹71,237 | ₹55,626 | ₹48,354 | ₹44,335 | ₹41,953 |
| ₹75 lakh | ₹89,046 | ₹69,533 | ₹60,442 | ₹55,419 | ₹52,441 |
| ₹1 crore | ₹1,18,728 | ₹92,710 | ₹80,589 | ₹73,892 | ₹69,921 |
A higher principal means a higher EMI because each instalment must repay more borrowed money. A longer tenure means a lower EMI because repayment is spread over more months. A longer tenure generally means higher total interest because interest accrues over a longer period. For a ₹50 lakh loan at 7.50%, a 20-year tenure results in approximately ₹46.7 lakh in total interest, while a 30-year tenure results in approximately ₹75.9 lakh—a difference of nearly ₹29 lakh.
LIC Home Loan Prepayment Calculator 2026
Part-prepayment is an extra payment made toward the loan principal, over and above the regular EMI. This amount directly reduces the outstanding principal balance, which in turn lowers the interest calculated in subsequent months. The earlier you prepay, the more interest you typically save, because interest is calculated on the reducing balance each month.
Part-prepayment vs full foreclosure: Part-prepayment is an additional payment during the loan\'s life, with the loan continuing. Full foreclosure (closure) means repaying the entire outstanding principal at once and ending the loan relationship.
After prepayment, borrowers typically can choose: (1) keep the EMI unchanged and reduce the remaining tenure, or (2) keep the original tenure and reduce the EMI. The available option depends on the lender\'s repayment instructions and the loan agreement. All prepayment calculations below assume EMI remains unchanged and tenure shortens, with the extra amount applied directly to principal.
LIC Home Loan Interest Savings with Monthly Prepayment
Base assumptions: Loan amount ₹40 lakh, illustrative annual interest rate 7.50%, original tenure 20 years, regular EMI approximately ₹32,236. The calculations below use a month-by-month amortisation schedule, with the extra payment made from month 1, applied directly to principal, and the EMI unchanged.
| Extra Monthly Payment | Estimated Payoff Period | Original Total Interest (approx.) | New Total Interest (approx.) | Estimated Interest Saved (approx.) | Estimated Time Saved |
|---|---|---|---|---|---|
| ₹0 (EMI only) | 20 years | ₹37.37 lakh | ₹37.37 lakh | — | — |
| ₹1,000 | About 17 years 4 months | ₹37.37 lakh | ₹31.2 lakh | About ₹6.2 lakh | About 2 years 8 months |
| ₹2,000 | About 15 years 3 months | ₹37.37 lakh | ₹26.6 lakh | About ₹10.8 lakh | About 4 years 9 months |
| ₹5,000 | About 10 years 11 months | ₹37.37 lakh | ₹18.2 lakh | About ₹19.2 lakh | About 9 years 1 month |
| ₹10,000 | About 7 years 9 months | ₹37.37 lakh | ₹11.9 lakh | About ₹25.5 lakh | About 12 years 3 months |
Interpretation: Paying ₹5,000 extra each month can shorten a ₹40 lakh loan from 20 years to under 11 years and save nearly ₹19 lakh in interest. Note that these are illustrative calculations based on a constant 7.50% rate; actual floating rate changes will alter the results.
LIC Home Loan Interest Savings with Annual Prepayment
Using the same base assumptions (₹40 lakh, 7.50%, 20 years, EMI ₹32,236), with the extra payment made at the end of every 12-month period.
| Annual Extra Payment | Estimated Payoff Period | Estimated Interest Saved (approx.) | Estimated Time Saved |
|---|---|---|---|
| ₹25,000 | About 16 years 8 months | About ₹7.5 lakh | About 3 years 4 months |
| ₹50,000 | About 14 years 2 months | About ₹13.8 lakh | About 5 years 10 months |
| ₹75,000 | About 12 years 4 months | About ₹18.5 lakh | About 7 years 8 months |
| ₹1,00,000 | About 10 years 10 months | About ₹22.3 lakh | About 9 years 2 months |
| ₹1,50,000 | About 8 years 7 months | About ₹27.4 lakh | About 11 years 5 months |
| ₹2,00,000 | About 7 years 1 month | About ₹30.8 lakh | About 12 years 11 months |
Note: The final prepayment should not exceed the outstanding principal balance at that point. The calculations above have been adjusted accordingly.
Monthly Prepayment vs Annual Prepayment
| Feature | Monthly Prepayment | Annual Prepayment |
|---|---|---|
| Payment frequency | Monthly | Once a year |
| Cash flow requirement | Smaller, regular amount | Large lump sum (e.g., bonus, annual savings) |
| Principal reduction pace | More frequent | Periodic |
| Interest impact | Earlier payments save more | Depends on timing |
| Suitable for | Those with regular monthly surplus | Those with annual bonus or lump-sum savings |
Monthly prepayment has the advantage of getting money into the principal sooner, which strengthens the interest-saving effect. Annual prepayment is easier to execute for borrowers whose income is concentrated in year-end bonuses. There is no universally \"better\" option—it depends on your cash flow pattern and discipline.
LIC Home Loan Prepayment Rules and Charges 2026
According to LIC Housing Finance\'s official MITC (Most Important Terms and Conditions) document:
During the floating-rate period, prepayment charges for individual borrowers are Nil.
During the fixed-rate period, if repayment is made from own sources, prepayment charges are Nil. If repayment is made from borrowed funds, a charge of 2% on the amount prepaid plus service tax applies (for individual borrowers only).
Non-individual borrowers (companies, partnerships, LLPs, trusts, etc.) or cases where a non-individual is a co-borrower: prepayment charges are 2% plus applicable taxes.
LIC HFL reserves the right to request evidence of the source of funds.
Items to confirm with LIC HFL: Minimum part-prepayment amount, frequency restrictions, whether a written request is required, and the default treatment after prepayment (EMI reduction vs tenure reduction). The final terms are governed by your sanction letter and loan agreement.
How to Use LIC Home Loan Prepayment to Close a Loan Faster
Check your outstanding principal balance through your LIC HFL account or statement.
Confirm your current applicable interest rate under the floating-rate structure.
Review prepayment terms for your loan type (floating vs fixed) and applicable charges.
Decide on the extra amount—start with a sustainable monthly or annual figure.
Submit the prepayment through an authorised channel following LIC HFL\'s specified process.
Confirm the payment is applied to principal, not held as advance EMI.
Request the revised repayment schedule to see the new remaining tenure or adjusted EMI.
Maintain an emergency fund—do not use all your savings for prepayment. Keep 3–6 months of living expenses as a buffer.
How Existing EMIs Affect LIC Home Loan Eligibility
Existing loans directly consume your monthly repayment capacity. Consider two applicants, both earning ₹60,000 per month:
Applicant A: No existing loans. Under a 40% illustrative budget, the available home loan EMI is ₹24,000, corresponding to an illustrative loan amount of about ₹29.8 lakh at 7.50% for 20 years.
Applicant B: Has ₹10,000 in existing EMIs (e.g., car loan + personal loan). The available home loan EMI drops to ₹14,000, corresponding to an illustrative loan amount of about ₹17.4 lakh.
Both earn the same salary, but B\'s indicative borrowing capacity is about ₹12.4 lakh lower than A\'s. This illustrates why reducing existing debt before applying for a home loan matters.
LIC Housing Finance Home Loan Documents Required
Salaried applicants typically need:
PAN card
Identity proof (Aadhaar, passport, etc.)
Address proof
Latest 3 months\' salary slips
6 months\' bank statements
Form 16 or income tax documents, where applicable
Employment-related documents (offer letter, employee ID, etc.)
Property documents (sale agreement, title deed, etc.)
Self-employed applicants may need business registration, financial statements, income tax returns, and other supporting documents. The exact checklist depends on the applicant and the property.
LIC Housing Finance vs Other Banks 2026
| Lender | Latest Verifiable Starting Rate | Prepayment Information |
|---|---|---|
| LIC Housing Finance | 7.40% (third-party data as of November 4, 2026) | Floating-rate individual loans: no charges |
| SBI | Not verified from official sources in this review | Typically no charges on floating-rate loans |
| HDFC Bank | Not verified from official sources in this review | Confirm with lender |
| Canara Bank | Not verified from official sources in this review | Confirm with lender |
| PNB | Not verified from official sources in this review | Confirm with lender |
| ICICI Bank | Not verified from official sources in this review | Confirm with lender |
Note: For lenders other than LIC HFL, official November 2026 starting rates could not be verified from available sources in this review. Rates vary by loan category, borrower profile, and loan amount. A lower \"starting rate\" does not necessarily apply to your specific profile. Compare actual offers from each lender based on your personal circumstances before deciding. LIC HFL is not necessarily the cheapest option in all cases.
FAQs – LIC Home Loan EMI Calculator with Prepayment Based on Salary 2026
How much LIC Housing Finance home loan can I get on a ₹30,000 salary?
Under a 40% illustrative EMI budget (₹12,000) at 7.50% illustrative rate, about ₹14.9 lakh for 20 years or ₹17.1 lakh for 30 years, assuming no existing EMIs. Actual eligibility depends on your credit profile and obligations.
How much home loan can I get on a ₹50,000 salary?
Same assumptions: about ₹24.8 lakh for 20 years or ₹28.6 lakh for 30 years.
What is the EMI for a ₹20 lakh LIC home loan?
At 7.50% illustrative rate: about ₹16,118/month for 20 years, or ₹13,984/month for 30 years.
What is the EMI for a ₹30 lakh LIC home loan?
At 7.50%: about ₹24,177/month for 20 years, or ₹20,977/month for 30 years.
What is the EMI for a ₹50 lakh LIC home loan?
At 7.50%: about ₹40,295/month for 20 years, or ₹34,961/month for 30 years.
Can I make monthly prepayments on my LIC home loan?
Yes. LIC HFL allows part-prepayment, and floating-rate individual loans carry no prepayment charges. Confirm the operational process with LIC HFL.
Does LIC Housing Finance charge for home loan prepayment?
Floating-rate individual home loans: No. Fixed-rate: no charge if paid from own sources; 2% + tax if paid from borrowed funds.
How much interest can I save by paying ₹5,000 extra every month?
On a ₹40 lakh, 7.50%, 20-year loan, paying ₹5,000 extra monthly is estimated to save about ₹19.2 lakh in interest and shorten the tenure by about 9 years. Actual savings depend on the real rate and timing.
Is annual prepayment better than monthly prepayment?
Not necessarily. Monthly prepayment gets money into the principal sooner and typically saves more interest; annual prepayment suits borrowers with lump-sum income such as bonuses.
Does prepayment reduce EMI or loan tenure?
Usually both options are available, depending on the repayment instruction you give the lender and the loan agreement. Confirm explicitly with LIC HFL.
Can I close my LIC home loan before the original tenure?
Yes. Floating-rate individual loans typically carry no prepayment penalty for full foreclosure.
What is the maximum LIC Housing Finance home loan tenure?
Up to 30 years, subject to borrower age and retirement age.
Does LIC Housing Finance offer floating-rate home loans?
Yes, LIC HFL home loans are primarily floating-rate products.
How can I calculate home loan eligibility based on salary?
Subtract existing EMIs and essential living expenses from your take-home salary to estimate the amount available for a home loan EMI, then use the reverse EMI formula or a calculator to find the corresponding loan amount.
What documents are required for an LIC Housing Finance home loan?
Salary slips, bank statements, Form 16, identity and address proof, employment documents, and property documents. Self-employed applicants need additional financial documents.



